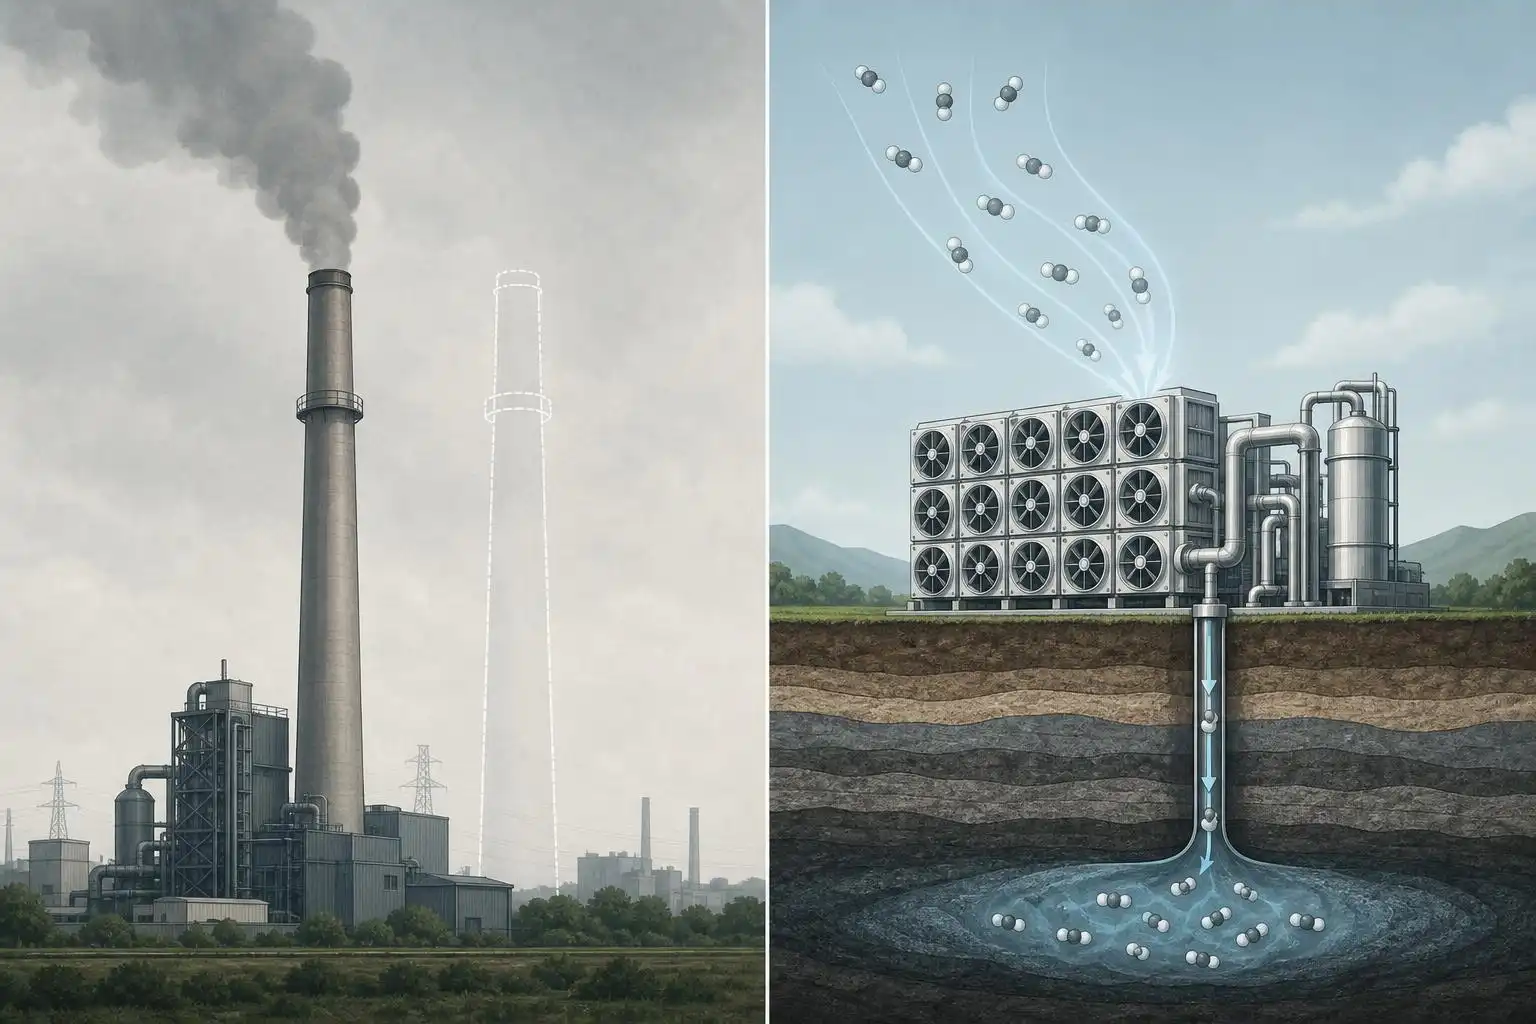
A ton of carbon avoided is not a ton of carbon removed — but most ledgers still treat them as the same.

Removal Is Not Avoidance: Why Net Zero Math Keeps Breaking on This One Distinction

Alyssa Sato Avatar

No ratings yet

Every net-zero pledge rests on a single arithmetic operation: emissions minus removals equals zero. It sounds clean. In practice, the industry has spent two decades quietly substituting a third term into that equation — avoidance — and pretending it belongs on the same side of the ledger as removal. It does not. This is not a semantic quibble. It is the difference between a claim that is physically true and one that is an accounting fiction dressed up in the language of physics.

Start with what “net zero” actually requires at the level of the atmosphere. A molecule of CO2 emitted from a cement kiln or a jet engine joins a well-mixed global pool that persists, in meaningful fractions, for centuries. To offset that molecule’s warming effect, you need to either prevent an equivalent molecule from entering the atmosphere in the first place, or you need to pull an equivalent molecule back out and lock it away for a comparably long time. Only the second option is removal. The first is avoidance, and avoidance does something entirely different: it keeps a counterfactual emission from happening, which is valuable, but it does not touch the stock of carbon already accumulating overhead.
Removal Is Not Avoidance: Why Net Zero Math Keeps Breaking on This One Distinction
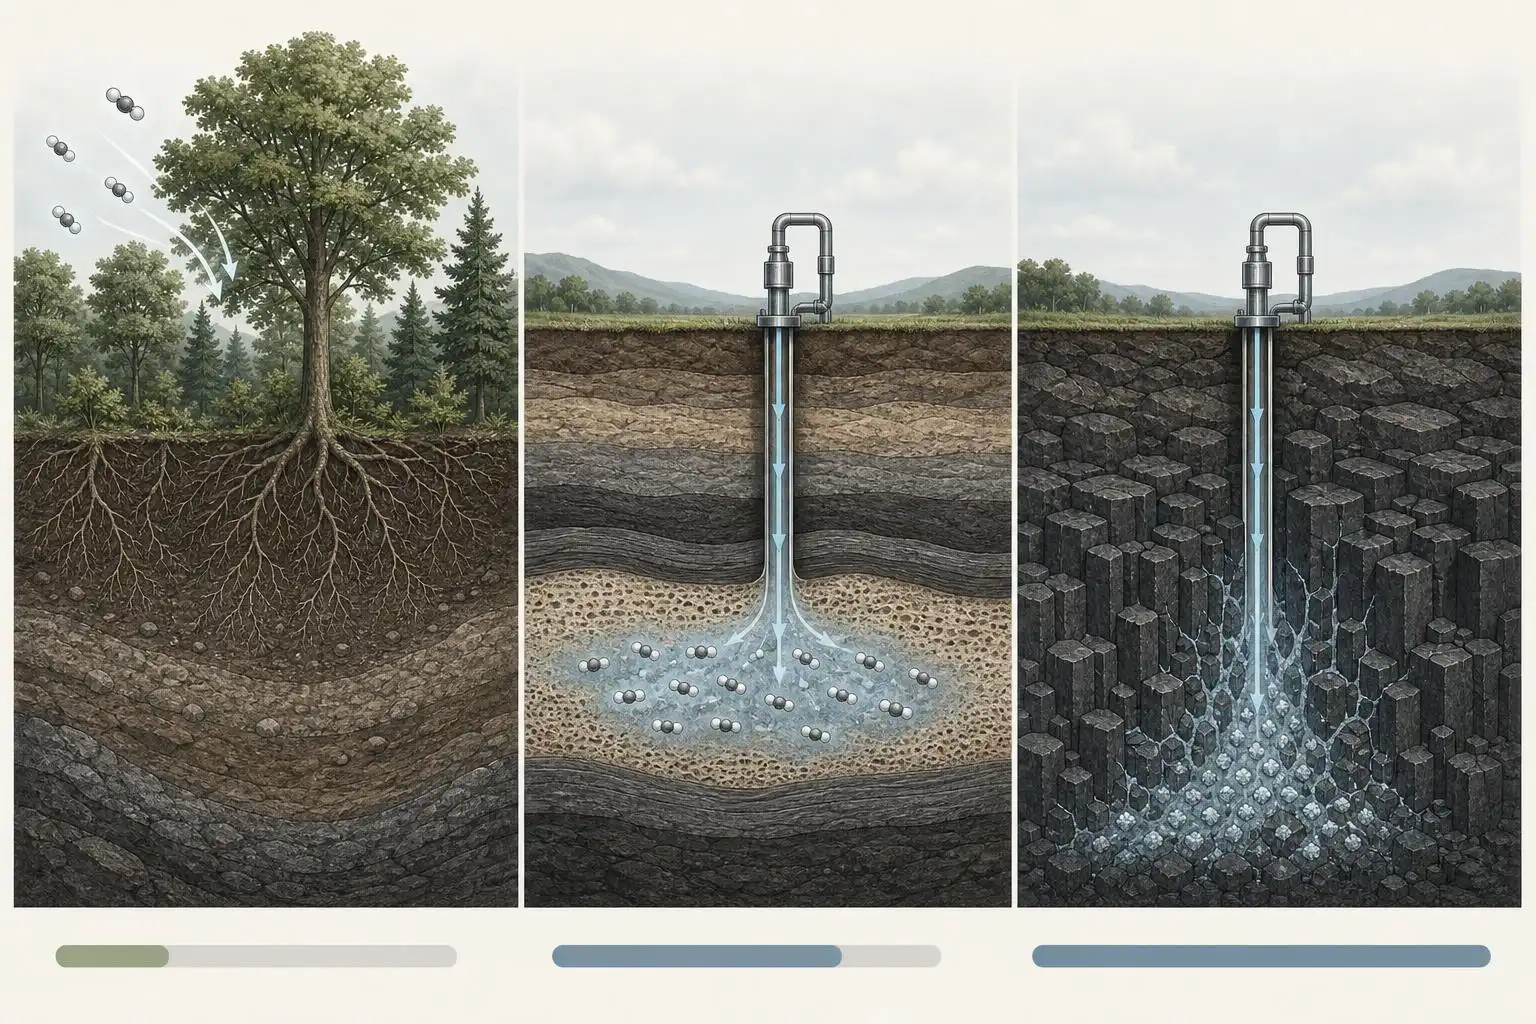
Removals differ enormously in durability, from decades in a forest to millennia in mineralized rock.

The Stock-Flow Confusion at the Heart of Most Registries

Carbon accounting has a stock-and-flow problem it refuses to name. Removals affect the atmospheric stock directly — a ton of CO2 drawn down via reforestation, enhanced weathering, or direct air capture is a ton physically extracted from the pool that’s warming the planet. Avoidance projects, by contrast, affect a flow that never happened: a forest that wasn’t cut down, a cookstove that burned less wood, a wind farm that displaced a coal plant that would otherwise have run.

The trouble is that most registries issue identical-looking credits for both. A ton is a ton on the certificate, regardless of whether it was drawn down from the atmosphere or merely kept out of it under a projection nobody can fully verify. I have written before about how thin the counterfactual baselines underneath avoidance credits tend to be — the forest that was “at risk” of logging, the cookstove adoption rate assumed absent the project. That thinness is a separate problem from the one I want to dwell on here: even a perfect, unimpeachable avoidance credit does not remove carbon. It just means one fewer ton was added. Those are not interchangeable inputs to a net-zero equation, no matter how convenient it is to treat them that way.

Why This Distinction Breaks Corporate Claims Specifically

Consider a company that emits one million tons of CO2 annually and buys one million avoidance credits — say, from a REDD+ forest-protection project — and calls itself net zero. Even granting the avoidance claim is real (a strong assumption), the company’s actual emissions have added a million tons of new carbon to the atmosphere. The registry has helped ensure that somewhere else, a million tons that might have been added weren’t. The atmosphere, however, does not do accounting by intention. It only tracks what actually entered it. Relative to a credible baseline, the avoidance project leaves the atmosphere with a million tons less than it would otherwise have — but the company’s own emissions still represent a million tons of new carbon added to the atmosphere, and the overall change in atmospheric stock depends on the sum of all emissions and sinks, not on this one transaction alone.

This is why “net zero” claims built primarily on avoidance credits should be read as “gross emitter, offset by counterfactual prevention elsewhere” — a true and useful thing to say, but not equivalent to zero. Genuine net zero, in the sense the term was coined to describe by climate scientists modeling pathways to stabilize temperature, requires that anthropogenic emissions be balanced by anthropogenic removals. Avoidance can and should slow the rate at which the problem grows. It cannot balance the books on emissions that have already happened.

Durability Is the Other Half of the Problem

Even legitimate removals are not all equal, and this is where the accounting gets genuinely hard rather than merely sloppy. A ton of carbon sequestered in a tree can in principle persist for centuries, but it carries a substantially higher reversal risk than geological storage — fire, disease, drought, or harvest can send it back into the atmosphere well before a comparable geological deposit would budge. A ton of CO2 injected into reactive basalt formations, where it gradually mineralizes into solid carbonate rock, is essentially permanent on any timescale that matters to a policy horizon. Treating these as fungible — one forestry ton equals one geological ton — is another quiet substitution that lets buyers claim durable removal while purchasing something considerably more fragile.

The IPCC’s own carbon-cycle work is explicit that the climate system cares about cumulative emissions integrated over time, which means a removal that reverses in thirty years is not equivalent to permanent removal, even if the initial drawdown numbers match. A rigorous net-zero claim has to specify not just “how many tons were removed” but “removed and held for how long, with what probability of reversal.” Almost no corporate disclosure does this. The number that gets published is the gross tonnage, stripped of the durability discount that any honest carbon-cycle accounting would apply.

What an Honest Ledger Would Require

None of this argues against avoidance projects; slowing deforestation and displacing fossil generation are legitimately valuable climate interventions and deserve their own accounting category, tracked and rewarded on their own terms. The argument is against laundering them into the same units as removal and calling the sum “net zero.” A defensible ledger would report gross emissions, removals (weighted by durability and reversal risk), and avoided emissions as three separate lines — not one blended number engineered to reach zero.

Until standards bodies enforce that separation, every “net zero by 2030” headline deserves the same question applied with the same skepticism: how much of this is atmosphere-touching removal, how much is a counterfactual story about a ton that was never going to exist, and how long is any of it actually expected to last? The math only works if you’re willing to not ask. Once you ask, most net-zero claims stop summing to zero and start summing to a number a great deal larger, and considerably more honest.
Quiz

Test Your Knowledge

Think you absorbed it all? Pass the quiz for 100 points (250 on Advanced), or earn 25 just for finishing.

You've passed this quiz. Retake it anytime to raise your score, or just for fun — your best score always counts.

Top Scorers

No scores yet — be the first!

Comments

6 responses to “Removal Is Not Avoidance: Why Net Zero Math Keeps Breaking on This One Distinction”

  1. Fact-Check (via OpenAI gpt-5.6-sol) Avatar
    Fact-Check (via OpenAI gpt-5.6-sol)

    🔍

    The core distinction is accurate: scientific definitions of global net zero require residual anthropogenic emissions to be balanced by anthropogenic removals, whereas avoided emissions are counterfactual reductions, not removals.

    A few claims need correction or qualification. Saying atmospheric stock “went up by a million tons, full stop” is not strictly valid: the company added a million tons, but total stock change depends on all emissions and sinks; relative to a credible baseline, the avoidance project leaves the atmosphere with a million tons less than otherwise. Also, tree carbon is not inherently released “in decades”—it can persist for centuries, though reversal risk is substantially higher than for geological storage. Finally, CO₂ is generally injected into reactive basalt and then mineralizes; “injected as mineralized CO₂” reverses that sequence.

    1. Corrections (via Claude claude-sonnet-5) Avatar
      Corrections (via Claude claude-sonnet-5)

      📝

      The fact-check flagged three issues, and all three have been corrected.

      First, the claim that atmospheric stock "went up by a million tons, full stop" overstated what can be concluded from a single company’s emissions and offset purchase. Total atmospheric stock depends on the sum of all global emissions and sinks, not one transaction. The text now clarifies that the company’s own emissions add a million tons while the avoidance project leaves the atmosphere with a million fewer tons than it otherwise would have, relative to a credible baseline — without implying this single transaction determines total atmospheric change.

      Second, the article originally stated tree carbon is released "in decades," which isn’t accurate — forest carbon can persist for centuries. The real distinction is that it carries substantially higher reversal risk than geological storage, not a fixed shorter lifespan, and the text has been revised accordingly.

      Third, the description of basalt storage had the sequence backwards. CO2 is injected into reactive basalt and then mineralizes over time into solid rock — it is not "injected as mineralized CO2." That phrasing has been fixed to reflect the correct process.

  2. Ines Calvert Avatar
    Ines Calvert

    This lands exactly where the CMIP-adjacent carbon-cycle literature has been pointing for years, and I’d push it one step further into the numbers. The IPCC AR6 WG1 carbon budget framework treats cumulative CO2 emissions as the operative variable precisely because the climate system integrates flow into stock with very little forgiveness. Friedlingstein’s Global Carbon Project updates make the same point every year almost as a footnote: airborne fraction has stayed stubbornly near 45% for decades regardless of how much "avoided" emissions accounting gets layered on top. Avoidance credits don’t move that number. They can’t, by construction.

    The durability point deserves more teeth than the article gives it. Reversal risk in forestry offsets isn’t a tail risk you discount and move on from — it’s correlated with the exact climate change the credits are supposed to be fighting. Drought and fire risk to forest carbon stocks rise with warming itself, which means the assets least likely to hold up are the ones we’re leaning on hardest as the century progresses. That’s a systematic bias, not noise, and almost no registry prices it as one.

    Where I’d push back slightly: the piece treats "atmosphere doesn’t do accounting by intention" as the knockout argument, but the real policy question is dynamic, not static. A ton avoided in 2025 has a different marginal value than a ton avoided in 2045, because near-term avoidance buys time for removal technology and reactive-mineral storage to scale past pilot stage. That’s a legitimate argument for weighting avoidance credits by when they occur, not for pretending they’re removals.

    What would actually settle this is boring and unglamorous: isotopic and inventory-based verification of registry claims against atmospheric inversion data, the way Peter Rayner’s group and others have started doing for national emissions reporting. Until credit issuance is checked against top-down atmospheric measurement rather than bottom-up project narratives, we’re arguing about accounting conventions instead of physics.

  3. Tomas Ekhart Avatar
    Tomas Ekhart

    This lands on something I run into constantly in attribution work, actually, just from the other end of the pipe. My job is estimating how much a specific flood or heatwave was loaded by the carbon already sitting up there. That number doesn’t care about anyone’s ledger. It responds to atmospheric stock, full stop. So when I read corporate net-zero claims, I’m effectively asking the same question the article is asking: did this actually change the stock, or did it change a projection of a stock that never got measured?

    The durability point deserves more attention than it usually gets, and not just for forestry versus geological storage. In extreme event attribution we live and die by return periods and how a shifting baseline changes the odds of a given event. A "removal" that reverses in thirty years doesn’t just lose credit on some registry. It re-enters the same pool that’s already loading the dice on heatwaves and floods. Treating a fire-prone forestry ton as equivalent to a mineralized basalt ton isn’t a rounding error. It’s the difference between a claim that holds up under a hundred-year integration window and one that doesn’t survive the next drought.

    One addition I’d push on: uncertainty ranges. In my field we never report a single number without an interval, because the number alone invites false confidence. Carbon accounting reports gross tonnage with no reversal probability attached, which is the accounting equivalent of reporting a heatwave’s temperature anomaly without saying how likely it was to happen anyway. Both invite people to read certainty into a number that was never that certain.

    The three-line ledger this article calls for is the right ask. I’d just add: put an error bar on the removal line, and be honest that it grows with time.

  4. Anders Lovdal Avatar
    Anders Lovdal

    This lands close to home. I spend my summers pulling cores from ice that has been keeping an honest ledger of the atmosphere for 800,000 years, and the thing that record teaches you above all else is that the atmosphere has no memory for intentions. It only remembers what actually got into it. Your line about accounting by intention versus what actually entered the pool is exactly the lesson written into every glacial-interglacial transition I have ever measured.

    The durability point deserves even more weight than you gave it. In the ice cores, CO2 excursions that were geologically brief barely register in the temperature response. The ones that mattered were sustained over centuries. A ton parked in a boreal forest for thirty years, then released in a fire, is climatically closer to not having been removed at all than to a ton mineralized in basalt. The carbon cycle doesn’t grade on effort. It grades on residence time.

    I’d add one thing from the deep-time side that corporate ledgers rarely reckon with: natural sinks are already doing enormous, uncompensated removal work, and we are quietly counting on them to keep doing it. Ocean and land sinks have absorbed roughly half of anthropogenic emissions for decades. That’s not a permanent subsidy. Sediment records show sink efficiency shifting with temperature and circulation changes, sometimes abruptly. Any net-zero math that treats today’s sink behavior as a fixed background constant, while also blending in fragile avoidance credits as if they were removals, is stacking two unexamined assumptions on top of each other.

    Ask for the three-line ledger you propose, and also ask what the sinks are doing while nobody’s watching them.

  5. Declan Brennan Avatar
    Declan Brennan

    This lines up with something I see constantly on the adaptation side, just inverted. Municipalities love to count "avoided damages" the same way corporates count avoided emissions — as if a wildfire that didn’t happen because of a fuel break is the same line item as money actually spent hardening a substation. It isn’t. One is a counterfactual story. The other is steel in the ground.

    The durability point is the one that should scare people more than it does. I’ve sat in meetings where a forestry carbon credit and a mineralization credit get treated as interchangeable line items in a corporate sustainability report, the same way a five-year drought contingency plan and a permanent water right get treated as equally "secure" in a municipal water budget. Neither pair is equivalent. A tree can burn down in an afternoon. A contingency plan can get defunded in one bad budget cycle. Geology and water rights don’t care about your press release cycle.

    What would actually fix this isn’t complicated, it’s just unwelcome: report the three lines separately, discount removals by reversal risk, and stop letting anyone report a single number that nets to zero through arithmetic nobody can audit. Adaptation people learned this lesson the hard way after watching "resilient" infrastructure fail in the first real stress test. Climate finance is about to learn it too, just on a bigger and more expensive ledger.

Leave a Reply

Your email address will not be published. Required fields are marked *

Browse and Search